Not every driver needs a conventional policy. broad form insurance is a named-driver form of auto coverage that can lower the premium, but it can also leave a driver, vehicle, or household member without the protection they expect. This guide from Auto Insure News explains broad form car insurance, broad form collision, availability, costs, and the questions to ask before buying.
What is broad form insurance coverage?
What is broad form car insurance? It is a limited, driver-based auto policy that usually provides liability protection for one named driver rather than physical-damage coverage for a particular vehicle. If that driver causes a crash, the policy may pay for another party’s bodily injury or property damage, subject to the policy limits, exclusions, and state requirements.
In other words, broad form auto insurance follows the listed driver while that person operates an eligible private-passenger vehicle for covered use. It is also called named-driver, named-operator, or “insurance on your license” coverage. A broad form auto policy can therefore work differently from a policy that lists each vehicle and household driver.
The phrase broad form insurance policy can be confusing: the name does not mean the policy offers broad protection. The broad coverage meaning in this context is about who the policy follows, not about covering every loss. People sometimes shorten the term to broad car insurance, but the contract—not the label—controls what is insured.
Broad form coverage is not the same as full coverage, which can add collision and comprehensive protection for the insured vehicle. It is also different from a standard family auto policy that can list multiple drivers and vehicles. The lower premium is the trade-off for these narrower protections.
What is broad form collision coverage?
Broad form collision coverage is not the same product as a broad form named-driver policy. A broad form auto policy usually covers one driver’s liability to other people; broad form collision is a vehicle-damage option that can pay to repair the insured vehicle after a crash.
For readers asking what is broad form collision or what does broad form collision mean, the answer is state-specific. Michigan, for example, treats broad form collision as one of its three collision choices and requires the coverage to pay collision damage to the insured vehicle regardless of fault, subject to the deductible rules in the policy. The Michigan DIFS auto-insurance guidance confirms that limited, standard, and broad form are different collision options.
Some sites use broadened collision, what is broadened collision, or broadened coverage as shorthand for a more favorable deductible or fault rule. Those terms are not interchangeable nationwide. Before relying on what is broad collision coverage, check the declarations page for the state, deductible, fault threshold, and exclusions that apply to your policy.
| Term | What it usually describes |
|---|---|
| Broad form auto policy | Driver-based liability coverage for one named operator; usually no damage coverage for the driver’s own vehicle. |
| Broad form collision coverage | A state-specific physical-damage option for a listed vehicle, with deductible and fault rules that vary by policy and jurisdiction. |
How broad form compares with standard and limited auto insurance
The labels standard, broad, and limited are not used identically by every insurer or state. To put this policy in context, review the different types of vehicle insurance and then confirm the definitions in the quote. Each form represents a different balance between premium and protection; “broad” does not automatically mean the widest coverage.
- Standard form: The conventional policy most drivers purchase. It may combine several coverages: liability, collision insurance coverage, comprehensive, uninsured/underinsured motorist protection, and optional add-ons, and can list multiple vehicles and drivers.
- Broad form: A liability-oriented policy that follows a single named driver. It may cost less than a standard policy because it provides narrower protection and commonly excludes collision, comprehensive, and coverage for other drivers.
- Limited form: In jurisdictions that use this label, a restricted collision or liability option may pay only under specified fault conditions. It may not satisfy state minimum requirements, so the policy wording and state rules must be checked.
| Form | Protection | Meets state minimum? | Relative cost |
|---|---|---|---|
| Standard | Broadest; multiple coverages, drivers, and vehicles | Yes | Highest |
| Broad | Liability for one named driver | Generally, yes, where offered | Low |
| Limited | Restricted protection; fault and exclusions vary | May not | Lowest |
How broad form car insurance works
In practice, broad form coverage functions like auto liability coverage, following the named insured rather than automatically protecting every driver of the insured vehicle. For a wider explanation of the product, review auto insurance explained.
Under a standard automobile policy, the insurer covers the vehicles and drivers listed on the declarations page. A broad form policy instead insures the named driver while operating eligible private-passenger vehicles for covered personal use, subject to exclusions for household-owned vehicles, commercial use, and other situations in the policy. If the named driver causes an accident, the liability component may cover the other party’s medical expenses and property damage repairs, up to the policy limits.
What broad form car insurance covers
In most cases, the policy provides a level of minimum liability insurance, although the precise scope depends on the insurer, the governing state, and the policy language. This is why broad form liability insurance should be compared by limits and exclusions—not by the monthly price alone.
The coverage afforded by broad form liability protection is concentrated in two areas: bodily injury and property damage.
Bodily injury liability
Bodily injury liability may pay for injuries the insured causes to another person in an at-fault accident. Covered costs can include medical treatment, emergency care, lost wages, and, in some circumstances, legal expenses arising from a claim. The amount payable is governed by the policy’s stated limits.
Property damage liability
Property damage liability may cover damage the insured causes to another party’s property, most commonly another vehicle, but may also include fences, signage, buildings, or other structures. The Washington State Office of the Insurance Commissioner explains that property damage liability helps pay for damage the insured causes to another vehicle or to property in an accident.
Summary of typical coverage
| Coverage type | Usually included? | Explanation |
|---|---|---|
| Bodily injury liability | Usually yes | Pays for injuries the insured causes to others |
| Property damage liability | Usually yes | Pays for damage the insured causes to others’ property |
| Named driver coverage | Yes | Protects the single person listed on the policy |
| Other drivers | Usually no | Other operators are generally not covered |
| Collision coverage | Usually no | Damage to the insured’s own vehicle is not covered |
| Comprehensive coverage | Usually no | Theft, vandalism, weather, and animal damage are not covered |
| Uninsured motorist coverage | Varies | May be optional, required, or unavailable by state |
| Medical payments / PIP | Varies | Depends on state law and insurer options |
What broad form car insurance does not cover
This section examines the policy’s exclusions, which are as significant as its inclusions. The lower premium associated with broad form insurance coverage is largely attributable to the omission of protections such as collision and comprehensive coverage.
A broad form policy generally does not cover damage to the insured’s own vehicle, nor does it extend coverage to other operators. A clear understanding of these exclusions is essential because assuming that broad form coverage works like full coverage can result in substantial uninsured losses.
Exclusion of other drivers
The most consequential limitation is the exclusion of other drivers. If a spouse, child, roommate, or colleague operates the insured vehicle, that individual may not be covered, even with the policyholder’s permission, because protection is restricted to the named driver. For households with multiple operators, a standard automobile policy that lists additional drivers is generally more appropriate.
Exclusion of damage to the insured’s own vehicle
Because liability insurance is designed to compensate third parties for harm caused by the insured, it does not automatically repair or replace the insured’s own vehicle. Protection of one’s own automobile generally requires collision coverage, which addresses crash-related damage, and comprehensive coverage, which addresses non-collision events such as theft, fire, hail, vandalism, and animal strikes.
Financed or leased vehicles
When a vehicle is financed or leased, the lender or lessor will ordinarily require physical damage coverage, typically collision and comprehensive. A liability-only broad-form policy may not satisfy those contractual requirements, and selecting it could cause the policyholder to violate the loan or lease agreement.
Additional exclusions: vehicle types, passengers, and endorsements
Beyond collision and comprehensive coverage, a broad form policy typically excludes several further categories of protection. Because the policy is confined to third-party liability for a single operator, it generally provides no coverage for the policyholder’s own passengers and cannot be supplemented with common endorsements.
- Specialised vehicles: Motorcycles, recreational vehicles (RVs), all-terrain vehicles (ATVs), and commercial vehicles are generally not covered. Drivers using a vehicle for business should ask an agent about a commercial policy rather than relying on a broad-form personal policy.
- The policyholder’s passengers: Injuries to the insured’s own passengers are typically not covered, unless the policy includes medical payments or personal injury protection.
- Theft and vandalism: Loss of personal property from the vehicle is not covered; a renters’ or homeowners policy may apply instead.
- Endorsements: Rental reimbursement, roadside assistance, and gap insurance are typically unavailable.
- Higher liability limits: The option to purchase additional liability coverage above the state minimum is generally not offered.
Limited availability
Broad form car insurance is not offered in every state, and even in states that permit it, not every insurer offers it. State statutes, insurance regulations, and individual underwriting practices all influence availability.
Where is broad form car insurance available?
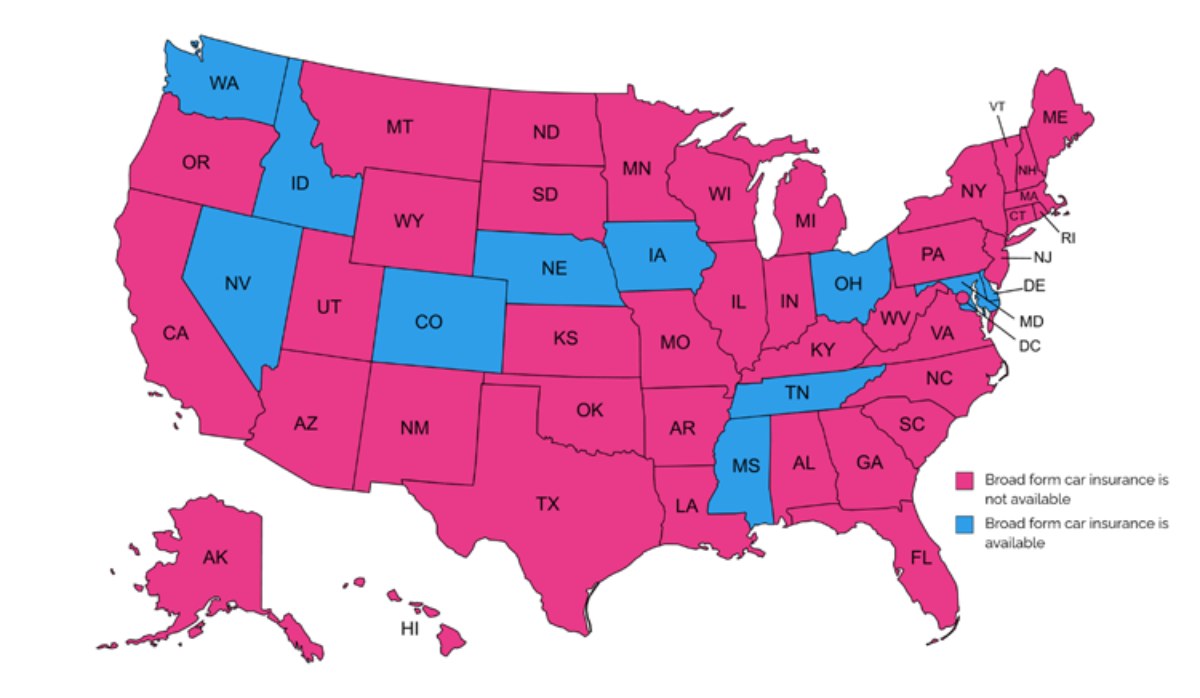
This section identifies where the product may be purchased. The list of broad-form car insurance states is limited because the narrow, single-driver structure is permitted only in certain jurisdictions.
A commonly cited list includes the following eleven states, but availability, minimum limits, and insurer participation can change. Treat this as a starting point and confirm eligibility with the state insurance department or a licensed agent before relying on a quote.
- Colorado
- Delaware
- Idaho
- Iowa
- Maryland
- Mississippi
- Nebraska
- Nevada
- Ohio
- Tennessee
- Washington
Even within these states, not every insurer markets the product. Some nonstandard carriers offer it as a minimum-level policy, while others offer only a standard liability or non-owner policy. Drivers outside the eligible jurisdictions should compare those alternatives instead of assuming a broad form quote is available.
How much does broad form car insurance cost?
Broad form coverage is frequently marketed as affordable auto insurance because it insures fewer risks than a conventional policy, but a lower premium reflects reduced protection rather than superior value.
There is no single price for broad form coverage, as cost depends on the same variables that influence any automobile premium. Rather than citing a fixed figure, which varies considerably by state and insurer, it is more instructive to examine the factors that raise or lower the premium.
Factors affecting the premium
- Driving record: Violations, prior accidents, or a DUI/DWI conviction can significantly increase the premium.
- Location: The insured’s state and ZIP code affect pricing.
- Coverage limits: Higher liability limits cost more but provide greater protection.
- SR-22 requirement: A filing can add fees and often signals a higher-risk profile, which may increase the premium.
- Insurer: Nonstandard carriers price these policies differently, so quotes should be compared.
Why a national average can mislead
There is no dependable national price for broad form car insurance. A published monthly average can combine different states, liability limits, driving records, and definitions of “broad form,” so it may not resemble a real quote. Compare the same limits and exclusions side by side, and review liability vs. full coverage before treating a lower premium as a saving.
| Quote factor | Why it changes the price |
|---|---|
| State, ZIP code, and required limits | Rules, claim costs, and minimum limits differ by jurisdiction. |
| Driving history and license status | Tickets, accidents, DUI/DWI records, and an SR-22 can increase risk-based pricing. |
| Vehicles and use | Personal-use eligibility, household-owned cars, commercial use, and vehicle type can trigger exclusions or a different policy. |
| Limits and optional protection | Higher liability limits and first-party coverages cost more but reduce out-of-pocket exposure. |
Broad form vs standard auto insurance and other alternatives
To situate broad form coverage among its alternatives, the following comparison contrasts it with non-owner car insurance, standard minimum (liability-only) coverage, and full coverage. The table clarifies which protections each option provides and the type of driver each is designed to serve.
| Feature | Broad form | Non-owner | Liability-only (minimum) | Full coverage |
|---|---|---|---|---|
| Meets state minimum liability | May; verify state limits | Usually; verify state rules | Yes if limits meet the law | Yes if limits meet the law |
| Higher liability limits available | Often limited; varies | Yes | Yes | Yes |
| Collision / comprehensive | No | No | No | Yes |
| Who is covered | Named insured only | Named insured (and co-insured) | Named/listed drivers; permissive use varies | Named/listed drivers; permissive use varies |
| Vehicles covered | Eligible vehicles the named driver operates, subject to exclusions | Borrowed or rented vehicles | Listed vehicles; permissive use varies | Listed vehicles and drivers, subject to policy terms |
| Best suited for | Sole drivers of low-value cars | Drivers who do not own a vehicle | Owners of older, paid-off cars | Owners of newer, financed, or leased cars |
Who should consider broad form car insurance?
The product may appeal to drivers seeking cheap car insurance with basic liability protection, but it is suitable only for a narrow group who drive alone and understand the associated financial risks.
The most suitable candidate is generally a single driver who owns an older, low-value vehicle and does not permit others to operate it. For such an individual, broad-form coverage may merit comparison with a standard liability-only policy.
Broad form coverage may be appropriate when the driver:
- Is the sole operator of the vehicle.
- Does not share the vehicle with family members, friends, or roommates.
- Owns an older vehicle of limited market value.
- Can afford to repair or replace the vehicle out of pocket.
- Requires only basic liability protection.
- Owns more than one vehicle but is the sole driver, if the insurer confirms that its broad form policy covers each eligible vehicle without a separate vehicle rating.
- Resides in a state where broad form coverage is permitted.
Broad form coverage may be inappropriate when the driver:
- Shares the vehicle with a spouse, partner, or teenage driver.
- Permits friends or roommates to borrow the vehicle.
- Finance or lease the vehicle.
- Requires full coverage protection for the vehicle itself.
- Cannot absorb significant repair or replacement costs.
- Must ensure multiple drivers or multiple vehicles.
Pros and cons of broad form car insurance
The value of broad-form coverage depends on whether its limitations align with the policyholder’s circumstances, much like other low-cost financial products.
Advantages
- Generally less expensive than standard automobile insurance.
- Simple structure suited to a single driver.
- May satisfy basic liability requirements.
- May be appropriate for older, low-value vehicles.
- Avoid paying for optional coverages you don’t need.
Disadvantages
- Covers only one named driver.
- Excludes other operators of the insured vehicle.
- Does not cover damage to the insured’s own vehicle.
- Typically omits collision and comprehensive coverage.
- May not satisfy lender or lease requirements.
- Is unavailable in most states.
- May provide inadequate protection after a serious accident.
The most common error is to regard broad form coverage as merely an inexpensive version of a standard policy. It is, in fact, a distinct product with a different risk profile.
How to get broad form car insurance quotes
A driver seeking car insurance for one driver should first determine whether broad-form policies are available in the relevant state, as availability is limited and regulated differently across jurisdictions.
Step 1: Confirm availability
Confirm with insurers or licensed agents whether broad form coverage is offered in the state, whether it is a named-driver policy, whether it satisfies state minimum requirements, and whether vehicle restrictions apply.
Step 2: Compare coverage line by line
Before choosing based solely on price, compare quotes using the same liability limits, named-driver restrictions, deductibles, and exclusions. The comparison should extend beyond the monthly payment to include liability limits, covered drivers, covered vehicles, exclusions, optional coverages, SR-22 availability, cancellation provisions, and the claims process.
Step 3: Compare against standard auto insurance
Obtain at least one quote for a standard liability-only policy, together with the cost of adding collision and comprehensive coverage. In some instances, the price difference is modest, and the broader policy represents better value.
Step 4: Select based on risk
If the applicant is the sole driver and can absorb the cost of repairing or replacing the vehicle, broad form coverage may be reasonable. If any other person is likely to operate the vehicle, the decision warrants careful reconsideration. Before deciding, compare what should i look for in car insurance, including exclusions and required limits.
Alternatives to broad form car insurance
Drivers who cannot purchase broad-form coverage or who require broader protection have several alternatives. In addition to the standard minimum-liability and non-owner car insurance options discussed above, certain states operate low-income automobile insurance programs for qualifying residents. Eligibility criteria, including income and driving history, differ by program. These rules also explain why is it mandatory to have car insurance in many situations.
- California: California Low Cost Automobile Insurance Program (CLCA)
- New Jersey: Special Automobile Insurance Policy (SAIP)
- Hawaii: Assistance to the Aged, Blind, and Disabled program (AABD)
- Maryland: Maryland Auto Insurance

RELATED AUTO INSURANCE GUIDES
Safety & Driving
How Does a Learner’s Permit Work? Rules and Next Steps
Safety & Driving
Thunderstorm Safety Tips at Home, Outdoors and in a Car
Auto Insurance
ACV vs Replacement Cost: How Insurance Payouts Differ
Safety & Driving
Black Ice on the Roads: How to spot it and handle a skid