Car insurance for married couples is often cheaper than coverage for a single driver, but marriage alone does not guarantee a lower premium. A spouse’s driving record, credit, state, vehicles, and policy structure can change the result. If you are just married, update your status and compare a combined quote with two separate policies before switching.
Is car insurance cheaper when married?
Usually, yes. Insurers in many states use marital status as one rating factor, and married drivers often receive lower quotes than single drivers with otherwise similar profiles. Recent rate analyses place the typical difference somewhere between 4% and 16%, or roughly $110 to $290 per year, depending on the state, insurer, driver profile, and coverage.
One important caveat: getting married does not automatically lower a premium. Insurers recalculate a rate only after they are notified of the change. Drivers who want the discount must update their marital status with their carrier; most allow a mid-term update rather than waiting until the next renewal.
Marital status is only one part of the quote. Auto Insure News also explains how age, location, vehicle, driving history, and coverage limits fit into the broader pricing formula.

Car insurance: married vs. single: how large is the difference?
The married-versus-single comparison varies by source because each analysis uses a different sample of drivers, states, and coverage levels. Rate data from The Zebra found that a married driver pays about $194 less per year than a single driver, an average discount of roughly 8%, and that the gap reaches as high as 15% in some states.
Other studies report a wider range. A Compare.com analysis found that married drivers paid an average of $124 per month, versus $151 for single drivers, a difference of about 16%, or $288 per year. A more conservative estimate from Way.com put the savings closer to 4%, or about $108 annually.
| Marital status | Avg. 6-month premium |
|---|---|
| Married | $1,051 |
| Widowed | $1,084 |
| Single | $1,148 |
| Divorced | $1,148 |
Average six-month premiums by marital status. Source: The Zebra.
| Source | Estimated savings vs. single | Annual dollar figure |
|---|---|---|
| The Zebra | ~8% | ~$194 |
| Compare.com | ~16% | ~$288 |
| Way.com | ~4% | ~$108 |
Because these are national averages, individual results vary. A driver’s age, home state, vehicle, and history all influence the final figure, and the marriage discount is only one piece of a larger pricing formula.
Does marriage change car insurance rates for every driver?
The marriage discount is not spread evenly across all drivers. Its size depends heavily on age and prior risk profile. Young drivers, who are statistically the most accident-prone and therefore pay the highest base premiums, tend to see the largest percentage drop when they marry. For more context on the factors insurers use, review how auto insurance rates are determined before separating the marriage discount from other pricing factors. The effect is especially pronounced for men under 25, a group insurers rate as high risk; even a modest percentage discount applied to their high premiums yields meaningful annual savings. Older drivers, whose premiums are already lower, generally see a smaller dollar difference.
Illustrative example: A 24-year-old man paying $3,000 a year as a single driver might see a 10–15% reduction after marrying a spouse with a clean record, saving about $300-$450 a year. A 45-year-old already paying $1,400 may save $60–$110 more because the base premium is lower and the risk profile is already favorable. Figures are illustrative; actual savings depend on the insurer and state.
How does the car insurance marriage discount work?
Married drivers file fewer claims
The primary reason is statistical. Insurers price coverage based on large groups’ claims history, and industry data has long shown that married policyholders file fewer and smaller claims than comparable unmarried drivers. Lower expected claims translate into lower premiums.
They are viewed as more financially stable
Carriers also associate marriage with stability and more predictable driving patterns, commuting, errands, and family trips rather than higher-risk behavior. That perceived stability feeds into the risk models used to set rates.
Multi-car discounts
Married couples frequently insure two vehicles on a single policy, which qualifies them for a multi-car discount. Such discounts typically range from 10% to 25%, depending on the insurer, and are one of the most concrete ways marriage lowers the combined bill.
Bundling home or renters insurance
Couples who combine auto coverage with homeowners or renters insurance can earn an additional multi-policy (bundling) discount, further reducing the total premium.
When does marriage not lead to lower car insurance rates?
Marriage does not guarantee a lower rate. Several situations can cancel out, or even reverse, the typical discount.
A spouse with a poor driving record
Adding a spouse who has at-fault accidents, a DUI, or multiple violations can raise the premium for both drivers on a shared policy. If the issue involves impaired driving, review DWI vs DUI to understand how terminology and insurance consequences can differ by state. In those cases, the added risk may outweigh the marriage discount.
A spouse with poor credit
In the states that allow credit-based insurance scores, adding a spouse with weak credit can increase the rate. If credit is one reason the combined policy becomes expensive, compare the combined and separate policy options before assuming one shared policy is cheaper. A handful of states restrict or ban the practice, but most permit it.
Adding a new or expensive vehicle
Bringing a second, newer, or higher-value car onto a policy raises the cost to insure it, which can offset savings from the marriage or multi-car discount.
Household composition
In some markets, adding more drivers and vehicles to a single policy, or including a teen driver, can push the combined premium above what two single drivers might pay separately. Families adding a young driver should compare the best auto insurance for teens before assuming the married-couple discount will offset the teen surcharge.
Illustrative example: If one spouse has a clean record and pays $1,300 a year while the other has a recent DUI and pays $3,400, combining both onto a single policy can spread the high-risk surcharge across the household and raise the clean driver’s share. In cases like this, keeping two separate policies until the violation ages off is often cheaper, which is exactly why comparing both options matters.
Marriage and car insurance: should you combine policies?
Combining policies is optional, and the right choice depends on both driving records. Being married does not automatically place a spouse on the other’s policy; the insurer must be notified to add a driver or vehicle.
- Combine when both records are clean. Couples with good driving histories and solid credit usually save the most by sharing one policy and stacking multi-car and bundling discounts.
- Consider separate policies when one spouse is high-risk. If one partner has recent accidents, violations, or poor credit, keeping policies separate, at least until the marks age off, can be cheaper.
- Always compare both options. The only reliable way to know is to request quotes for both a combined policy and two separate policies, then compare the totals. Use the same coverage limits, deductibles, vehicles, drivers, and garaging address when learning how to get auto insurance quotes as a married couple.

Just married? What to do with your car insurance
When it comes to getting married and car insurance, the discount is not automatic: drivers must notify their insurer of the marriage to have the rate recalculated. The process is usually straightforward:
- Notify the insurer promptly. Most carriers allow a mid-term change in marital status rather than requiring drivers to wait until renewal.
- Have both drivers’ details ready. The insurer will need each spouse’s license number, date of birth, and driving history.
- Decide how vehicles are listed. This affects which cars qualify for the multi-car discount and how each is rated.
- Ask for a re-quote both ways. Request the combined-policy price and compare it against keeping two separate policies.
- Bundle other coverage. Ask about adding renters or homeowners insurance at the same time for an additional multi-policy discount.
Do I select single or divorced for car insurance?
If your divorce is final and the quote form lists divorced as an option, select that status rather than choosing single simply because you no longer share a policy. If you are separated, or the form only offers “single” and “married,” ask the insurer which definition it uses. Report the change promptly, especially if one spouse moved, a vehicle changed ownership, or the household drivers changed.
Does marital status affect car insurance in every state?
Not uniformly. Most states allow insurers to treat marital status as a rating factor, provided the difference is supported by actuarial data, and, where applicable, the married-versus-single gap can reach around 15%. But the dollar impact varies enormously by location. A 2026 MoneyGeek analysis found that married couples save anywhere from $190 to $3,726 a year compared with two separate single-driver policies, with Florida showing the largest gap and Vermont the smallest.
States that restrict or effectively ban marital-status pricing
A handful of states have decided it is unfair to price coverage on personal characteristics rather than driving behavior, and they limit or prohibit the practice:
| State | How marital status is treated |
|---|---|
| California | Heavily restricted under Proposition 103; driving record, mileage, and experience must be the primary rating factors, so marrying or divorcing barely moves the rate. |
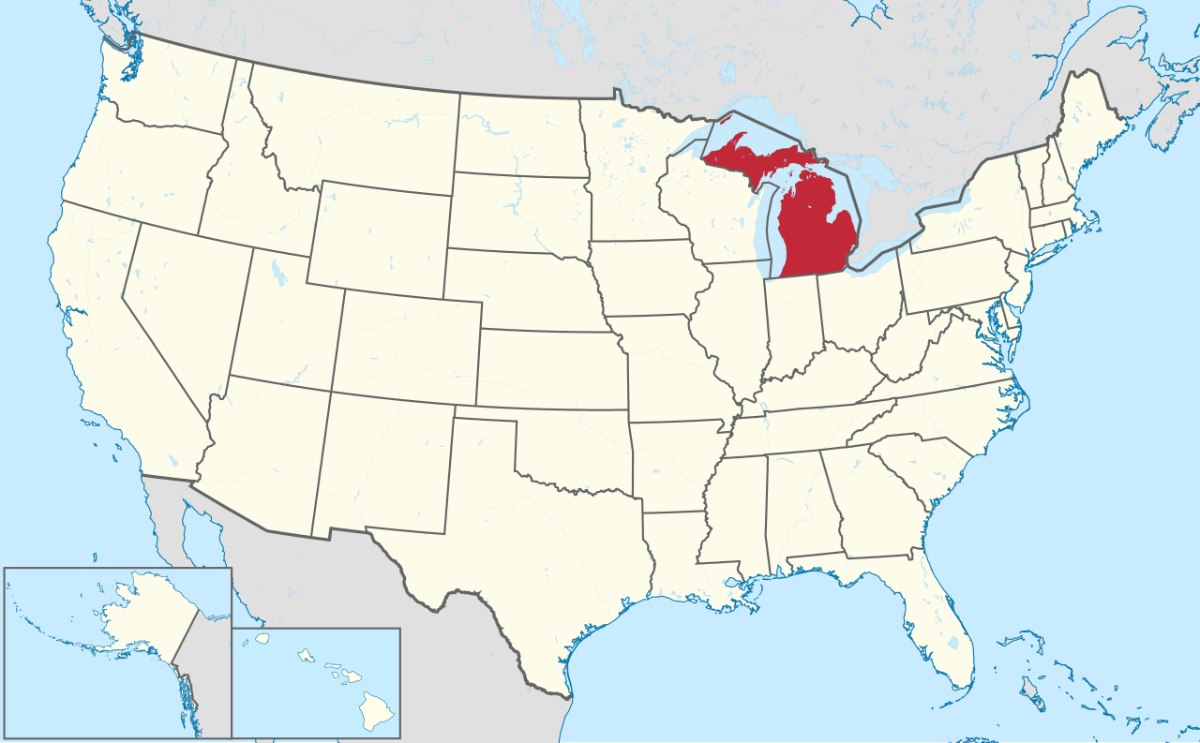
| Michigan | Illegal to use marital status (or gender) as a rating factor. |
| Massachusetts | Among the most restrictive states; sharply limits non-driving personal factors. |
| Hawaii | Bars many non-driving factors, including marital status, from pricing. |
| Maryland | Prohibits raising a widow’s premium solely because a spouse has died. |
The ‘widow penalty’
Where the factor is allowed, the loss of a spouse can actually raise a driver’s rate. Research by the Consumer Federation of America found that several major insurers, including GEICO, Farmers, Progressive, and Liberty Mutual, charged widows roughly 20% more than married drivers for the same coverage, while State Farm did not vary its prices by marital status. Consumer advocates have urged regulators to scrutinize the practice as unfair to unmarried, divorced, and widowed drivers.
Where the trend reverses
Marriage does not lower the bill everywhere. In some high-cost markets, such as New York, combined policies for married couples can carry higher premiums simply because they tend to cover more drivers and vehicles on a single policy. The lesson is that state rules and local pricing can matter as much as marital status itself.
Changing laws to watch
Those rules are not static. In California, a 2025 challenge (Ison v. Commissioner of Insurance) has asked the state Court of Appeals to decide whether charging different rates based on marital status is lawful under Proposition 103 and state civil rights law. In Montana, by contrast, a court in March 2026 upheld a law allowing insurers to set rates based on sex and marital status. At the federal level, a proposed bill known as the PAID Act would bar insurers nationwide from using marital status, along with factors such as gender, credit score, and ZIP code, to set rates. None of these changes is settled, so confirm the current rules in your state before relying on an older quote or article.
How to get the cheapest rate as a married couple
The practical way to find the marriage discount is to compare quotes. Couples should request rates for a combined policy and for two separate policies, ask each insurer about multi-car and bundling discounts, and confirm how a spouse’s record or credit affects the total before making a switch. These steps can also help with saving money on car insurance.
The best time to review your coverage is before an accident or a policy renewal, not after a claim. When comparing a combined married-couple policy to two separate policies, use the same liability limits, deductibles, vehicles, and garaging address so you are comparing like-for-like; otherwise, a lower price may simply mean less protection. To make that first step easier, use the Auto Insure News form at the bottom of this page: enter your email and state to get tailored rate-comparison tips, savings alerts, and coverage updates, free with no spam and unsubscribe anytime.
For most couples, marriage brings a modest but real reduction in car insurance costs, typically 4% to 16%. The savings are driven less by marriage itself than by the lower claim rates of married drivers and by discounts for insuring two cars or bundling policies. The benefit is largest for younger drivers and smallest for those who already pay low premiums. It is not guaranteed: a spouse with a poor record or weak credit can wipe out the discount, and a few states limit how much marital status can affect pricing. A sensible next step is to notify the carrier, then compare combined and separate quotes before deciding.

RELATED AUTO INSURANCE GUIDES
Safety & Driving
Hot Car Safety Tips for Children, Pets and Drivers
Safety & Driving
How Does a Learner’s Permit Work? Rules and Next Steps
Safety & Driving
Thunderstorm Safety Tips at Home, Outdoors and in a Car
Auto Insurance
ACV vs Replacement Cost: How Insurance Payouts Differ